Irreplaceable Adriatic coastline. A global luxury brand. Investor-first terms.
Privaat Capital invites accredited and professional investors to take a direct equity position in Smokva Bay d.o.o., the freehold land-owning company developing the Nammos resort and residences, through Privaat Capital EU Fund I (Nammos), LLC.
- Land owned and debt-free: ~1.2 km of west-facing freehold coastline, independently valued at about US$53M.
- Planning approved: approvals secured for both development phases.
- Brand signed: a fully executed Hotel Management Agreement with Nammos.
- Delivery partner: Mereha Development LLC, whose experience includes Atlantis The Royal, Dubai.
- Aligned fees: the management fee is paid only after investors receive their capital back.
Why this opportunity
Irreplaceable land
About 1.2 km of west-facing freehold coastline on the Budva Riviera, debt-free and independently valued at about US$53M.
De-risked entitlements
Planning approvals for both phases are secured, removing a key risk of coastal development.
Signed global brand
An executed Nammos Hotel Management Agreement supports premium room rates and branded-residence pricing.
Proven delivery partner
Mereha Development LLC manages development; its experience includes Atlantis The Royal, Dubai.
Early cash generation
Phased sales of residences and mansions produce cash during construction and reduce the equity requirement.
EU accession upside
The front-runner EU candidate targets membership by 2028. The sponsors estimate US$58–93M of upside, none of it in the base case.
Direct equity
Invested directly in the land-owning company, with a board seat, minority protections and use-of-funds controls sought.
Investor-first terms
Fee paid only after capital is returned, 100% fee offset, 8% preferred return, escrow and Manager co-investment.
Nammos Luxury Residences
An ultra-luxury beachfront resort and a limited collection of branded homes on a rare, large and contiguous stretch of freehold Adriatic coastline. Residences can join an asset-light rental pool managed with the resort, earning hospitality income for owners and the Project alike.
| Component | Description |
|---|---|
| Nammos beachfront resort | Ultra-luxury resort operated under a fully executed Hotel Management Agreement with Nammos |
| 61 branded estate residences | Nammos-branded homes with resort services and an optional rental pool |
| 9 beachfront mansions | Trophy residences directly on the waterfront — the scarcest product in the scheme |
| Land | ~1.2 km west-facing freehold coastline, debt-free, independently valued at ~US$53M |
| Approvals | Planning approvals secured for both development phases |
Smokva Bay d.o.o.
Project Company · freehold land owner and developer
Mereha Development
Development Manager · Atlantis The Royal experience
Nammos
Hotel operator · executed Hotel Management Agreement
Privaat Capital
Manager of Privaat Capital EU Fund I (Nammos), LLC
Partner information as provided by the Project sponsors. Full agreements are available in the data room after NDA.
A destination on the Adriatic
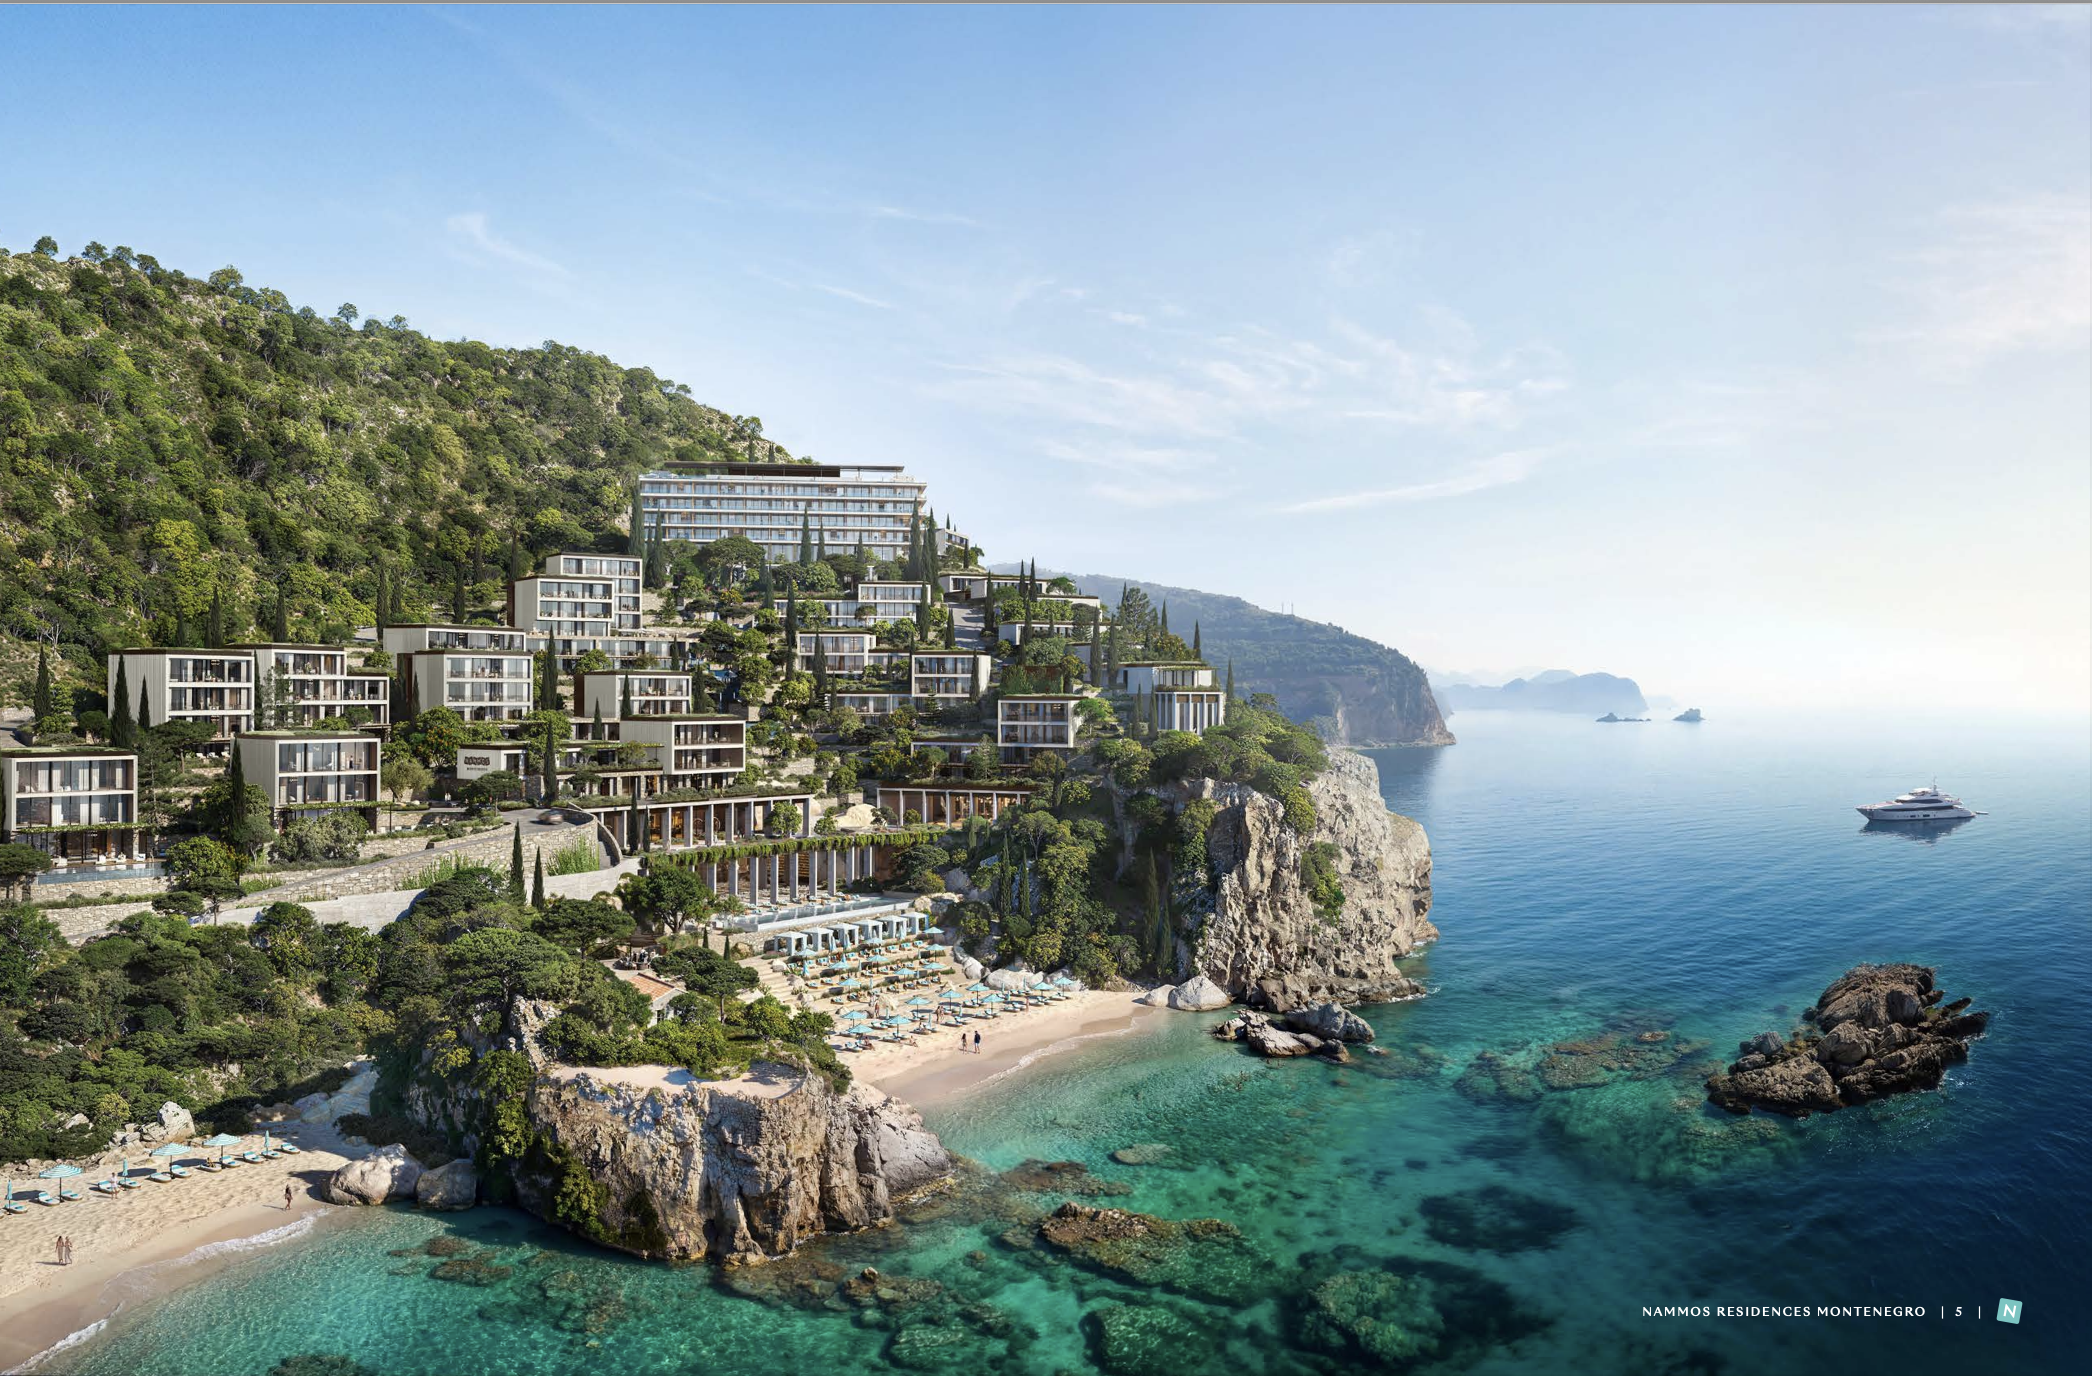
Renderings and imagery are illustrative and may not reflect the final design.
Montenegro: a coast in ascent
The coast drives Montenegro’s tourism economy, and the country is the front-runner to become the European Union’s next member. Both trends support demand for branded luxury product and institutional exit liquidity.
Sources: MONSTAT (2025); Trading Economics (August 2026).
EU accession — the structural catalyst
Sources: PISM (Aug 2026); OSW (Jul 2026); Euronews (Apr 2026).
Potential cap-rate compression
The sponsors estimate, from comparable accession markets, that EU membership could compress hospitality cap rates by 150–250 bps, worth about US$58–93M of additional value. Because timing is uncertain, this upside is excluded from the base case.
Already on the euro
Montenegro uses the euro, which aligns pricing with European buyers and removes Project-level currency conversion.
Sponsor base case
| Metric | Value |
|---|---|
| Estimated gross residential development value | ~US$418M |
| Estimated total development cost | ~US$263M |
| Land contributed by sponsors (independent valuation) | ~US$53M |
| New equity capital required | ~US$209M |
| Projected unleveraged investor IRR | >25% |
| Projected project MOIC | ~4.77x |
| Projected NPV (11% discount rate) | ~US$174M |
| EU accession upside (not in base case) | US$58–93M |
Capital structure
Total development cost of ~US$263M, funded by sponsor land equity and new equity. Residential pre-sales reduce the new equity needed.
$53M
~$161M
$48M
Value creation
- Development margin: ~US$418M residential value against ~US$263M total cost.
- Brand premium: Nammos supports premium pricing for residences and rooms.
- Recurring income: resort operations and the rental pool.
- Exit options: residential sell-down, an asset or company sale, or refinancing.
Sponsor projections converted from euros at US$1.16/€ (GDV ~€360M; development cost ~€226.5M; land ~€46M; new equity ~€180M; NPV ~€150M). Projections depend on significant assumptions, have not been independently verified, and may not be achieved.
Terms designed around the investor
| Issuer | Privaat Capital EU Fund I (Nammos), LLC — Delaware LLC, taxed as a partnership |
| Managing Member / Manager | Privaat Capital US GP, LLC (Delaware) / Privaat Capital Investments & Participations FZCO (Dubai) |
| Raise | Up to US$50,000,000 · Units at US$1,000 · First Closing at US$10,000,000 |
| Eligible investors | U.S. accredited investors (Rule 506(c), verified) and non-U.S. professional investors (Regulation S) · capped at 99 investors |
| Minimum | US$500,000 (individuals) · US$1,000,000 (entities) |
| Unit classes | Class A, and Founding Class F (subscriptions at the First Closing, or US$5M+) |
| Management fee | 1.5% (A) / 1.0% (F) per annum — paid only from distributions after capital is returned |
| Project fee offset | 100% of fees paid by the Project to Privaat Capital on Fund capital are credited to investors |
| Waterfall | Return of capital → 8% compounded preferred return → 50/50 catch-up → 80/20 (A) or 85/15 (F) |
| Escrow | Funds held by a U.S. escrow agent; refunded in full if the First Closing is not reached |
| Manager commitment | At least the lesser of 1% and US$500,000, on investor terms |
| Expenses | Organisational costs capped at 1%; placement agent fees borne by the Manager |
| Currency and reporting | All in U.S. dollars; quarterly reports; audited U.S. GAAP accounts; Schedules K-1; Privaat Connect portal |
| Governance | Advisory Committee of the largest unaffiliated investors; key-person and removal rights |
| Term | Target realisation Q4 2029, with up to two one-year extensions |
How the terms compare
| Term | Common private real estate fund terms | This offering |
|---|---|---|
| Management fee | 1.5–2.0% a year from day one, charged on committed capital | Paid only after investors receive their capital back |
| Fees from portfolio company | Often retained wholly or partly by the manager | 100% credited to investors |
| GP catch-up | Commonly 100% | 50% — investors keep more of the early profit |
| Carried interest | 20% | 20%, or 15% for Founding investors |
| Funding risk | Capital called into a blind pool | Single, identified asset; escrow until the First Closing |
“Common terms” describes typical market practice for closed-ended private real estate funds and varies by manager. Full terms are set out in the PPM and LLC Agreement.
Model your net outcome
Adjust the inputs to see how the Fund’s terms translate a Project-level return into an investor-level outcome. This is a hypothetical arithmetic illustration, not a forecast.
Assumes a single investment at the First Closing and a single realisation; 1.0% organisational costs and 0.6% p.a. operating costs deducted from capital; management fee subordinated to return of capital; 8% compounded preferred return; 50% catch-up; carried interest of 20% (A) or 15% (F). The withholding tax option applies 15% to the gain only, before any treaty relief or foreign tax credit. No currency movement assumed. Actual results will differ and may be negative.
Scenario table — US$1,000,000 subscription, three-year hold
| Project-level gross return | Class A net | Class F net | Class A after 15% WHT |
|---|---|---|---|
| 30% | 1.92x · 24.2% | 1.97x · 25.4% | 1.78x · 21.1% |
| 25% (sponsor base case) | 1.73x · 20.0% | 1.77x · 21.0% | 1.62x · 17.4% |
| 15% | 1.39x · 11.6% | 1.41x · 12.2% | 1.33x · 10.0% |
| 8% | 1.22x · 6.8% | 1.22x · 7.0% | 1.18x · 5.7% |
| 0% | 0.97x · -0.9% | 0.97x · -0.9% | 0.97x · -0.9% |
Use of proceeds
| Application | US$ | % |
|---|---|---|
| Equity investment in Smokva Bay d.o.o. | 48,000,000 | 96.0% |
| Fund expense reserve (full term) | 1,500,000 | 3.0% |
| Organisational and offering costs (capped) | 500,000 | 1.0% |
| Total | 50,000,000 | 100% |
Placement agent fees are borne by the Manager. The management fee is never paid from invested capital.
Direct equity, institutional governance
Protections sought for the Fund
Board seat
A board seat or observer right, with monthly development and sales reporting.
Minority vetoes
Over budget overruns, new debt, related-party deals, new equity and changes to the Hotel Management Agreement.
Anti-dilution
Pre-emption rights on the remaining new equity raise.
Use-of-funds controls
Capital released against verified construction milestones.
Exit rights
Tag-along, drag-along and a liquidity mechanism if there is no exit by Q4 2030.
Compliance covenants
Sanctions and AML screening of all residential buyers.
Why a Delaware LLC
- Familiar: U.S. private fund market-standard vehicle and documents.
- Tax-transparent: no entity-level U.S. tax; U.S. investors may be able to claim foreign tax credits.
- No U.S. assets: non-U.S. investors are generally not expected to have U.S. filing obligations.
Reporting and oversight
- Quarterly reports: construction, sales, budget and capital accounts.
- Annual audit: U.S. GAAP accounts and Schedules K-1.
- Advisory Committee: reviews conflicts, extensions and valuation.
- Privaat Connect: a secure investor portal for documents and updates.
A discreet capital gateway
Privaat Capital Investments & Participations FZCO is a Dubai-based private equity and capital advisory firm within the Privaat Group, operating across the UAE, the United States and Europe. It works with family offices, professional investors and strategic counterparties on curated private transactions.
Hospitality and real estate
Leadership-level transaction experience, including senior roles at Savills and Christie & Co.
Cross-border reach
Structuring and investor access across the Gulf, the United States and Europe.
Skin in the game
Manager co-investment on investor terms; fees paid only after investors’ capital is returned.
Our approach
- Selective: each opportunity is curated for a limited group of qualified investors, never mass-marketed.
- Institutional process: self-certification and NDA, then the PPM and full data room.
- Transparent: direct access to the integrated financial model, technical due diligence, development programme and legal documentation.
Risks and mitigants
This investment carries substantial risk, including the loss of all capital. The key risks are summarised below; the full Risk Factors are set out in the Private Placement Memorandum.
Construction cost overruns and delays
Residential sales below plan
Minority position in the Project Company
Funding of the remaining new equity
Montenegro country and legal risk
EU accession delays
Currency (EUR/USD)
Tax
Illiquidity and transfer restrictions
Natural hazards
Mitigants reduce but do not eliminate risk.
From first conversation to Founding investor
Documents
Request the PPM and data room
Registering interest is not a commitment to invest. Privaat Capital will contact you to confirm eligibility and arrange the NDA.
Questions investors ask
Who can invest?
How is accredited status verified for U.S. investors?
What is the minimum investment?
What happens if the First Closing is not reached?
What fees do I pay?
When do I get my money back?
Is everything in U.S. dollars?
How am I taxed?
Can I transfer my Units?
What will I receive as an investor?
Legal notices
Not an offer
This page has been prepared by Privaat Capital Investments & Participations FZCO (“Privaat Capital”) for information only. It is not an offer to sell, or a solicitation of an offer to buy, any security. Any offer will be made only by the Confidential Private Placement Memorandum (the “PPM”), the Limited Liability Company Agreement and the Subscription Documents of Privaat Capital EU Fund I (Nammos), LLC (the “Fund”), which qualify this page in its entirety.
U.S. securities law
The Units have not been registered under the U.S. Securities Act of 1933, as amended (the “Securities Act”), or the securities laws of any state. They are offered in the United States only to accredited investors in reliance on Rule 506(c) of Regulation D, and outside the United States only to non-U.S. persons in offshore transactions in reliance on Regulation S. The Fund will take reasonable steps to verify that U.S. purchasers are accredited investors. The Fund will not be registered under the U.S. Investment Company Act of 1940. The Units are subject to restrictions on transfer and resale, including a one-year distribution compliance period for Units sold under Regulation S. Neither the SEC nor any state securities regulator has approved or disapproved of the Units or passed upon the accuracy or adequacy of this page.
Jurisdictions
This page is directed only at persons to whom it may lawfully be communicated: in the UAE, DIFC and ADGM, professional investors or Professional Clients (the Fund is a foreign fund not regulated or approved by the SCA, DFSA or FSRA); in the United Kingdom, investment professionals and high-net-worth or sophisticated investors exempt under the Financial Promotion Order (the Fund is an unregulated collective investment scheme); in the EEA, professional investors in member states where the Fund may lawfully be marketed under the AIFMD; and in Switzerland, Hong Kong and Singapore, qualified, professional or accredited investors. It must not be acted upon by any other person. Offers and sales to U.S. persons are made through a FINRA-member placement agent.
Forward-looking information
This page contains projections and other forward-looking statements, including Project costs, values and returns prepared by the Project sponsors. Privaat Capital has not independently verified them, and they may not be achieved. Illustrative and calculator returns are hypothetical arithmetic illustrations of the Fund’s terms, not forecasts, and do not reflect actual investor experience. Euro figures are converted at an indicative US$1.16 per euro. Images and renderings are illustrative.
Risk
An investment in the Fund is speculative and illiquid, involves a high degree of risk, and is suitable only for investors who can afford to lose their entire investment. Prospective investors should read the PPM, including its Risk Factors and Conflicts of Interest, and consult their own legal, tax and financial advisers.
Data protection
Information submitted through this page is used by Privaat Capital only to respond to your enquiry and assess eligibility, and is not sold to third parties. See the privacy policy at privaatcapital.ae/legal.
Sources
Project information: Project sponsors, via privaatcapital.ae. Market data: MONSTAT; Trading Economics; PISM; OSW; Euronews.